
An economic system that can create trillions for financial markets somehow struggles to find the money for ordinary people. Maybe the problem isn’t a lack of money. Maybe it’s who the system is designed to serve.
“No economist can explain why the Fed prints money but also borrows money. Because economy majors are trained stooges to justify an unjust system.”
— Me
The moment the economic establishment couldn’t explain itself
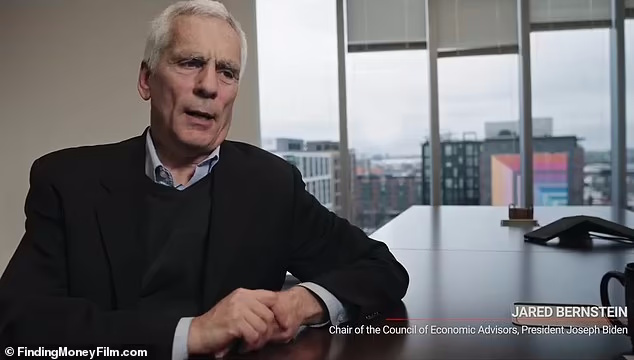
There is a moment in an interview with Jared Bernstein, former chair of President Biden’s Council of Economic Advisers, that deserves to be remembered. The question is straightforward: if the United States can create its own currency, why does its government need to borrow that currency?
Bernstein begins explaining. He hesitates. He tries to put the pieces together. He suggests that the government prints money and then lends it through the sale of bonds. He starts again, loses his thread, and eventually admits that he doesn’t really understand what the interviewer is asking.
The clip is repeated later in the interview, and it is worth watching both times. The first time, you might laugh. The second time, you might wonder why someone occupying such an influential economic position struggles to explain one of the most fundamental questions about the system he helps advise.
Of course, one awkward interview doesn’t prove that an economist knows nothing about economics. Nor does it mean that the question has no answer. But it does expose a remarkable disconnect between the language used to justify government policy and the monetary mechanisms that policy actually relies on.
And that disconnect matters, because we are constantly told that public spending has to be restrained, that national debt threatens our future, and that ordinary people must accept cuts to essential services because the money simply isn’t there.
Yet when the financial system faces a crisis, enormous sums suddenly become available.
So where does the money come from, and why are we told there isn’t enough of it?
First, let’s ask the question properly
The United States has its own currency. The federal government issues Treasury securities, commonly called government bonds, while the Federal Reserve manages monetary policy and can create central bank reserves.
These are related institutions with different legal responsibilities. The Treasury doesn’t simply operate a printing press whenever Congress wants to spend, and the Federal Reserve doesn’t directly buy newly issued Treasury securities at auction. The distinction matters, but it doesn’t make the underlying question disappear.
When the government spends more than it collects in taxes, it runs a deficit. The Treasury finances that deficit through borrowing, primarily by issuing securities. Those securities become assets for the people and institutions that buy them, and the government promises to pay interest according to their terms.
The question is why this arrangement exists when the monetary system has the capacity to create dollars.
Modern Monetary Theory, or MMT, offers one explanation. As economist L. Randall Wray and other proponents argue, a government that issues its own floating currency operates differently from a household, a business, or a country that owes debt in a currency it cannot issue. Treasury securities can be understood partly as interest-bearing assets held by the private sector, rather than evidence that the United States might literally run out of dollars.
That distinction changes the entire conversation.
If government debt is routinely presented as a household credit-card bill, people are encouraged to imagine that every public service competes for a finite pile of dollars that must first be collected from taxpayers or borrowed from wealthy investors. The actual monetary system is more complicated than that.
And the political implications are enormous.
Why issue bonds at all?
The conventional explanation is that government spending exceeds tax revenue, so the Treasury borrows the difference. The bonds provide a way to finance deficits, manage government cash flows, and supply financial markets with assets that investors consider relatively safe.
There are also monetary-policy reasons for maintaining a market in government securities. Treasury bonds are central to financial markets, influence interest rates, serve as collateral, and provide savings instruments for banks, pension funds, investment funds, households, and foreign governments.
MMT advocates take the argument further. They point out that the government can issue currency-denominated liabilities and that Treasury bonds can be viewed as a way of exchanging one form of government liability for another: dollars in the financial system are exchanged for interest-bearing securities.
Under this interpretation, the national debt is not comparable to a household that has borrowed money it cannot possibly earn. It represents outstanding government liabilities, including securities held by investors.
That doesn’t make the debt imaginary. The securities are real, the interest payments are real, and the distribution of those payments has real consequences.
It does, however, raise a question that is almost entirely absent from the usual political debate: why have we designed the system to pay interest to holders of government debt, and who benefits most from that arrangement?
Issuing bonds serves legitimate financial and monetary purposes. Whether the existing arrangements are necessary in their current form, and whether their benefits justify their costs, are political questions. They should be debated openly rather than treated as laws of nature.
Follow the interest
Imagine two people living in the same country.
The first works for a living, pays taxes, rents an apartment, and watches housing costs rise faster than wages. Saving enough for a deposit feels increasingly impossible.
The second owns substantial financial assets, including government bonds. Those bonds generate interest payments backed by the government’s capacity to meet its obligations.
Both live under the same economic system, but they experience it very differently.
Government debt can provide useful, secure savings instruments for pension funds and ordinary households. The interest doesn’t go exclusively to billionaires. Nevertheless, wealthy households and large financial institutions have much greater capacity to hold substantial amounts of interest-bearing assets and accumulate additional wealth from them.
The result is a distributional question that deserves far more attention than the headline debt figure: who receives the income generated by government borrowing, and who bears the political pressure to reduce spending?
When politicians invoke the national debt to justify austerity, the public is asked to consider the costs of government spending. Much less attention is paid to the costs of interest payments, the ownership of government securities, or the alternatives available to policymakers.
The system can be defended as financially necessary without anyone having to defend its distributional consequences.
That is where my criticism begins.
The government finds money for Wall Street
Look at the response to financial crises.
During the 2008 financial crisis, the US government and Federal Reserve intervened on an extraordinary scale to stabilize the financial system. The interventions included emergency lending, bank support, guarantees, and asset purchases. These were different programs with different mechanisms, and they should not all be casually described as the government handing banks a single pot of newly printed money.
But the broader point remains: when the financial system was threatened, policymakers were willing to use public institutions and enormous financial resources to prevent a systemic collapse.
Then came the pandemic. The government authorized trillions of dollars in fiscal support, while the Federal Reserve took extraordinary monetary-policy measures. Some households received direct assistance, but the response also supported businesses and financial markets. The distribution of that assistance, including the benefits that accrued to asset owners, deserves serious scrutiny.
Why did the political system find ways to intervene on such a scale in those moments, while affordable housing, healthcare, public infrastructure, and economic security remain subjects of endless arguments about what the country can afford?
There are real constraints on public spending. Money creation cannot conjure up missing houses, hospital beds, trained workers, energy, or food. Spending beyond the economy’s productive capacity can contribute to inflation, and poorly designed programs can waste resources or enrich politically connected interests.
But those constraints make the question of what we spend on even more important.
If public resources are limited by the real capacity of the economy, shouldn’t we prioritize the things that enable people to live secure, productive lives?
Why should a financial institution’s stability be treated as an emergency requiring immediate action, while a family’s inability to afford a home is treated as an unfortunate market outcome?
The difference is not simply accounting. It is political power.
Inflation is more complicated than the money-printing story
One of the most persistent arguments against government spending is that creating more money automatically makes every existing dollar worth less.
That is too simplistic.
Inflation depends on several interacting forces, including demand, productive capacity, supply disruptions, energy costs, market concentration, and the ability of businesses to raise prices. An increase in spending can contribute to inflation when demand exceeds the economy’s ability to supply goods and services. Its effects depend on where the money goes, when it is spent, and what the economy can produce in response.
The pandemic illustrated this complexity. Supply chains were disrupted, production was constrained, demand shifted, and substantial fiscal support sustained purchasing power. Those factors interacted in ways that cannot be explained by pointing to a single number representing money creation.
Nor does this mean that money creation is harmless. If a government injects substantial purchasing power into an economy already constrained by shortages, prices can rise. If spending expands productive capacity, improves infrastructure, or brings unused resources into productive use, the consequences can be different.
The point is that inflation is an economic problem to investigate, not a magic phrase that ends every discussion about public spending.
The same scrutiny should apply to corporate pricing power, monopolies, speculation in housing, and the effects of interest-rate policy. A system that treats wage increases and public benefits as inflation risks while giving insufficient attention to concentrated market power deserves to be challenged.
Housing has become an investment vehicle
Perhaps nowhere are these contradictions more visible than in housing.
A home is a basic human need. It is also an asset that can appreciate in value, generate rental income, and serve as collateral for further investment. When financial incentives encourage the treatment of housing primarily as an investment, the interests of property owners can diverge sharply from the interests of people trying to find somewhere to live.
Existing homeowners may benefit from rising prices. Investors may welcome scarcity if it supports rents and asset values. People trying to enter the market face larger deposits, bigger mortgages, and fewer affordable options.
Public policy can reinforce these incentives through land-use rules, tax treatment, credit conditions, infrastructure decisions, and the way housing is financed and supplied.
Government bailouts and monetary interventions can also affect asset prices and financial conditions, although their effects vary by program and period. The benefits are not distributed equally.
This is the larger problem with an economic system that measures success through asset appreciation and financial returns while treating the cost of basic necessities as somebody else’s problem.
A country can become wealthier on paper while becoming less affordable for the people who live in it.
The stock market can rise while renters struggle. Property portfolios can expand while young adults postpone buying their first home. Financial wealth can accumulate without a corresponding improvement in the everyday security of the population.
When policymakers tell us that the national debt is the central danger, we should ask whether they are paying enough attention to the economic conditions that debt policy is supposed to serve.
The real problem with economics
This brings me back to the economist in that interview.
My criticism isn’t that every economics graduate is stupid or dishonest. Plenty of economists do valuable research, challenge conventional assumptions, and document the effects of inequality. There are serious disagreements within the profession about money, deficits, inflation, and the proper role of the state.
My concern is that economic education can teach people to accept the existing institutional framework as the starting point for every discussion. Students learn how markets work, how governments finance spending, how central banks set interest rates, and why policymakers make particular choices. Yet the question of who benefits from those arrangements can receive far less attention than the mechanics themselves.
The result is an intellectual culture in which an arrangement can be treated as necessary simply because it is familiar.
If a government issues bonds, we are told it must borrow. If it pays interest, we are told that is the cost of responsible financial management. If it cuts public services, we are told the budget requires discipline. If it supports financial markets, we are told the stability of the entire economy is at stake.
Each explanation may contain part of the truth. The problem arises when the explanation is used to shut down further questions.
Who designed these rules? Who benefits from them? Who pays the price? What alternatives exist? And what would happen if the same urgency applied to the material needs of ordinary people?
Those are economic questions too. They are also questions about power.
The national debt is a political choice
The United States does not have unlimited access to real resources. Its government cannot spend without consequences, and a currency issuer cannot guarantee that every spending program will be productive, sustainable, or free from inflation.
But neither can we understand the national debt by pretending that the federal government is simply a household with a larger checking account.
The government issues liabilities in its own currency. Treasury securities provide income to their holders. Deficits can add net financial assets to the non-government sector. Taxes influence demand, redistribute income, and sustain demand for the currency, among other functions. Monetary policy affects credit conditions and interest rates. These mechanisms operate together, and their consequences depend on the choices made by policymakers.
Once we understand that, the debate changes.
Instead of asking only how to reduce the deficit, we can ask what the deficit accomplishes. Instead of treating every dollar of public spending as a threat, we can examine its effects on productive capacity, living standards, and the distribution of wealth. Instead of assuming that interest payments are simply an unavoidable feature of government finance, we can debate how the bond system should operate and whether its present structure serves the public interest.
And instead of accepting austerity as a technical necessity, we can ask why the burden of economic adjustment so often falls on those with the least power.
So what’s really happening?
The interview is revealing because a seemingly basic question opens the door to a much bigger debate. The monetary mechanics are complicated, but the public should not have to accept a system simply because its rules are presented in technical language.
Economists you see called on the news to discuss “what’s happening now” are the most delusional people – yet the most successful economy graduates. Being a consultant for a news network is their dream job. They have no perspective how dumb and unfair the system is.
If you ask me : this system was established to be both a servitude for the workers through debt and inflation – and a funnel for the ultra rich. And since the FED, it has been carefully perfected to create this effect. It worked so well, governments left and right implemented quantitative easing and bonds across most modern economies.
Either they’re too deep in it and dumb to understand it, but still benefit – or they’re the true holders of power and they manipulate it the most.